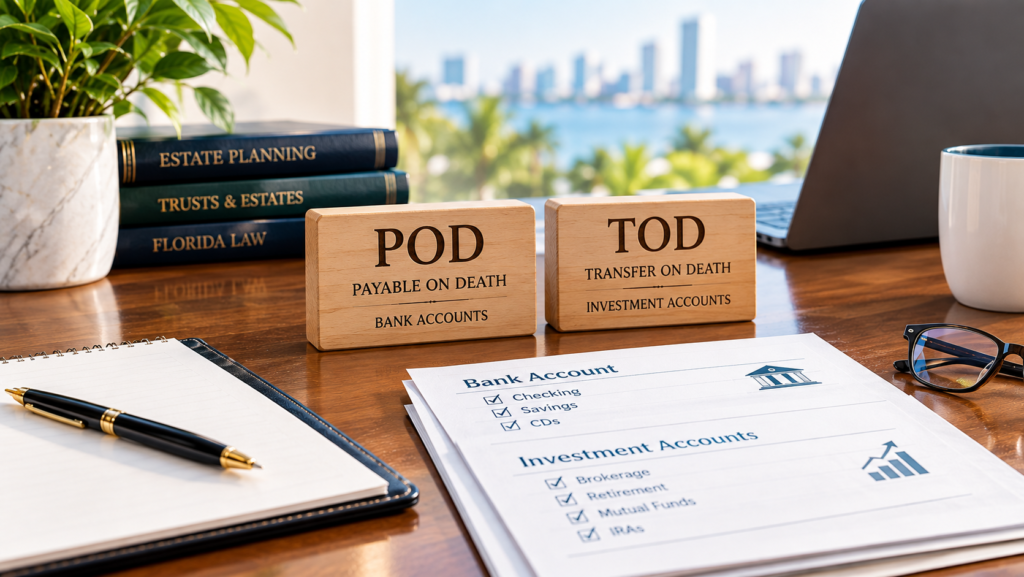
Many Florida families assume their savings, checking, and brokerage accounts will be handled by their will. In reality, a will sends those accounts straight into probate court, which can freeze the money for months. Two simple tools solve this problem for most financial accounts: the payable on death (POD) designation and the transfer on death (TOD) designation.
Both designations let you name a beneficiary who receives the account directly when you die, without a court case, without a personal representative, and without waiting for creditor deadlines. This guide explains what a POD account is, what a TOD account is, how POD vs TOD compares in Florida, the bank account beneficiary rules you need to know, and where these designations fit inside a complete estate plan.
Quick answer: POD and TOD accounts work the same way but apply to different assets. A POD designation is used on bank accounts such as checking, savings, money market accounts, and CDs. A TOD designation is used on investment accounts such as brokerage accounts, stocks, bonds, and mutual funds. Both are non probate assets, which means the named beneficiary can claim the funds with a death certificate and identification, usually within a few weeks.
What Is a POD Account?
A POD account, short for payable on death account, is a bank account with a named beneficiary who receives the balance when the account owner dies. In Florida, POD accounts are governed by Section 655.82 of the Florida Statutes, which applies to banks, credit unions, and other financial institutions.
During your lifetime, the beneficiary has no rights to the money at all. You can withdraw funds, close the account, or change the beneficiary whenever you want without anyone’s permission. The beneficiary’s interest only becomes real at the moment of your death. At that point, the bank pays the balance directly to the beneficiary, and the account never becomes part of your probate estate.
You may also see POD accounts called “in trust for” (ITF) accounts or Totten trust accounts. These labels describe the same basic arrangement: a bank account payable to a named person at death.
Common Types of Bank Account Payable on Death Designations
- Checking and savings accounts at banks and credit unions
- Certificates of deposit (CDs)
- Money market deposit accounts
- U.S. savings bonds, which use a similar POD beneficiary registration through the Treasury
What Is a TOD Account?
A TOD account, short for transfer on death account, is an investment or securities account with a named beneficiary who receives ownership of the assets when the owner dies. Florida adopted the Uniform TOD Security Registration Act, found in Sections 711.50 through 711.512 of the Florida Statutes, which allows securities and brokerage accounts to be registered in beneficiary form.
Just like a POD account, a TOD account gives the beneficiary no rights while you are alive. You keep full control over buying, selling, and withdrawing. When you die, the brokerage firm re-registers the account or the securities in the beneficiary’s name, often without selling anything. That means the beneficiary can keep the same investments rather than receiving cash.
Assets That Commonly Use a Brokerage Account TOD Designation
- Individual and joint brokerage accounts
- Individual stocks and bonds held in registered form
- Mutual fund accounts
- Treasury securities held through a brokerage
Retirement accounts like IRAs and 401(k)s work in a similar way, but they use their own beneficiary designation forms rather than a TOD registration. The rules for those accounts, including required distributions for heirs, are covered in the guide on how beneficiary designations work in Florida.
POD vs TOD: What Is the Difference?
When people search for TOD vs POD, they often expect a major legal difference. The truth is that the two designations do the same job. The main difference is the type of asset each one covers and the Florida statute that governs it.
| Feature | POD (Payable on Death) | TOD (Transfer on Death) |
|---|---|---|
| Assets covered | Bank accounts, CDs, credit union accounts | Brokerage accounts, stocks, bonds, mutual funds |
| Florida law | Section 655.82, Florida Statutes | Sections 711.50 to 711.512, Florida Statutes |
| What the beneficiary receives | Cash balance of the account | Ownership of the securities, often transferred without sale |
| Beneficiary rights during your life | None | None |
| Can you change the beneficiary? | Yes, anytime | Yes, anytime |
| Avoids probate? | Yes | Yes |
| Typical time for heirs to receive funds | Days to a few weeks | A few weeks, depending on the firm |
| Controlled by your will? | No | No |
In short, the POD and TOD comparison comes down to where your money is held. If it sits in a bank, you want a POD designation. If it sits with a brokerage firm, you want a TOD designation. Many Florida families use both.
How POD and TOD Accounts Avoid Probate in Florida
Florida probate only covers assets titled in the deceased person’s name alone with no beneficiary and no surviving co-owner. Because a POD or TOD account has a named beneficiary, the account passes by contract with the financial institution rather than through the court. That makes these accounts non probate assets.
Here is what the process usually looks like for the beneficiary:
- The beneficiary contacts the bank or brokerage firm and reports the death.
- The beneficiary provides a certified death certificate, a government-issued photo ID, and any claim form the institution requires.
- The institution verifies the designation on file and pays out the funds or re-registers the securities in the beneficiary’s name.
Compare that to probate, where the same account could remain frozen until a personal representative is appointed and the creditor period has expired. If you want to understand just how long that wait can be, the article on how long probate takes in Florida breaks down each stage of the timeline.
Other Common Non Probate Assets in Florida
POD and TOD accounts are only one category of non probate assets. Others include life insurance with a named beneficiary, retirement accounts with a beneficiary designation, jointly owned property with rights of survivorship, Florida homestead property that passes under the homestead rules, real estate transferred by a Lady Bird deed, and any asset titled in the name of a revocable living trust. A full overview of these strategies is available in the guide on how to avoid probate in Florida.
Bank Account Beneficiary Rules in Florida
Adding a bank account beneficiary is easy, but the rules behind it can surprise families who never read the fine print. These are the Florida bank account beneficiary rules that matter most.
The Beneficiary Designation Overrides Your Will
A POD or TOD designation is a contract with the financial institution, and it controls who receives the account no matter what your will says. If your will leaves everything equally to three children but your largest savings account names only one child as POD beneficiary, that one child receives the entire account. This is one of the most common causes of family conflict after a death, and it is a key reason to review your designations whenever you update or change your will.
Multiple Beneficiaries Share Equally Unless Stated Otherwise
If you name more than one POD beneficiary on a Florida bank account, the surviving beneficiaries generally share the balance equally. Some institutions allow you to set different percentages, while others do not. Always confirm how the bank will divide the funds.
If a Beneficiary Dies Before You
If your only POD or TOD beneficiary dies before you and you never name a replacement, the account typically falls back into your estate and goes through probate. Some brokerage firms allow a “per stirpes” or LDPS designation that passes a deceased beneficiary’s share to their children, but many banks do not offer this option.
Minors Cannot Directly Receive Large Amounts
Naming a minor child or grandchild as a POD or TOD beneficiary often creates problems. Under Florida law, a court-supervised guardianship of the property is generally required when a minor inherits more than $15,000. A better approach is usually to name a trust for the child’s benefit as beneficiary, or to use a custodial arrangement under the Florida Uniform Transfers to Minors Act if the institution permits it.
Joint Owners Come Before POD Beneficiaries
If an account is jointly owned with right of survivorship and also has a POD beneficiary, the surviving joint owner takes the account first. The POD beneficiary only receives the funds after the last joint owner dies.
FDIC Insurance Coverage for POD Accounts
Under the FDIC rules that took effect in April 2024, POD and other trust accounts are insured up to $250,000 per beneficiary, with a maximum of $1,250,000 per owner per bank for up to five beneficiaries. Families with large cash balances should confirm how their coverage is calculated with their bank.
Advantages and Limits of POD and TOD Accounts
Why Florida Families Use Them
- Free and simple. Most banks and brokerages let you add a beneficiary with a one-page form at no cost.
- Fast access for heirs. Beneficiaries usually receive funds within days or weeks instead of months.
- Private. Unlike probate filings, POD and TOD transfers are not part of the public court record.
- Full lifetime control. You keep complete ownership and can change or remove the beneficiary at any time.
Where POD and TOD Designations Fall Short
- No incapacity protection. A POD or TOD designation only works at death. If you become incapacitated, your family will still need a healthcare surrogate for medical decisions and a durable power of attorney to manage your accounts.
- No control after the transfer. The beneficiary receives the money outright. There is no way to stagger distributions, protect a beneficiary with creditor or spending problems, or preserve eligibility for government benefits.
- Easy to forget. Designations made years ago may still name an ex-spouse, a deceased relative, or only some of your children.
- Uneven results in blended families. A single designation can unintentionally disinherit a spouse or stepchildren, which is why estate planning for blended families in Florida usually calls for a coordinated plan rather than account-by-account choices.
- No help paying final expenses. If all of your cash passes by POD and TOD designations, your estate may have nothing left to pay funeral costs, final bills, or taxes, leaving the personal representative in a difficult position.
POD and TOD Accounts vs. a Revocable Living Trust
POD and TOD designations are excellent for simple situations. For families who want more control, a revocable living trust is often the better foundation. A trust can hold bank and investment accounts, real estate, and personal property under one set of instructions, with a successor trustee who manages everything if you become incapacitated and distributes assets according to your wishes after death.
Many Florida estate plans combine both tools. Accounts are either retitled into the trust as part of the process to fund a revocable living trust, or the trust itself is named as the POD or TOD beneficiary. Naming the trust as beneficiary keeps the account out of probate while letting the trust’s terms control timing, protections for minors, and division among children. Choosing the right person to carry out those terms matters, and the guide on how to choose a successor trustee in Florida explains what to look for.
| Question | POD / TOD Designation | Revocable Living Trust |
|---|---|---|
| Avoids probate? | Yes, for that account only | Yes, for all funded assets |
| Covers real estate? | No (Florida uses a Lady Bird deed instead) | Yes |
| Manages assets during incapacity? | No | Yes, through the successor trustee |
| Controls how and when heirs receive money? | No, paid outright | Yes |
| Protects minor beneficiaries? | No, may require guardianship | Yes |
| Cost to set up | Usually free | Attorney fee to draft and fund |
If you are weighing these options, the article on probate vs. trust administration shows how each path plays out for the family, and do I need a will if I have a trust explains why a pour-over will still matters as a safety net for anything left outside your plan.
How to Set Up a POD or TOD Account in Florida
- List every account. Include checking, savings, CDs, credit union accounts, brokerage accounts, and mutual funds.
- Request the beneficiary form. Most banks and brokerages offer POD or TOD forms online or at a branch.
- Name primary and contingent beneficiaries. Use full legal names and, where allowed, include a contingent beneficiary in case the primary beneficiary dies first.
- Coordinate with your estate plan. Make sure the designations match the goals in your will or trust, especially if minors, blended family members, or beneficiaries with special needs are involved.
- Keep written confirmation. Ask the institution for confirmation that the designation was recorded and store it with your estate planning documents.
- Review after major life events. Marriage, divorce, a birth, or a death in the family are all reasons to revisit every designation.
What Happens to a POD or TOD Account After Death
Once the bank or brokerage releases the account, the money belongs to the beneficiary. Still, POD and TOD accounts are not entirely free from obligations. Under Florida law, if the probate estate does not have enough assets to pay valid claims, expenses of administration, and certain family allowances, non probate transfers can in some circumstances be reached. Federal estate tax, if it applies, is calculated on your entire estate, including POD and TOD accounts.
If the account owner received Florida Medicaid benefits for long-term care, it is also important to understand how Medicaid estate recovery in Florida works, since the state’s claim is filed against the probate estate. For a broader look at the steps families face in the weeks after a loss, the guide on what happens after someone dies in Florida walks through each one.
Frequently Asked Questions
What is the difference between POD vs TOD accounts?
What is a POD account?
What is a TOD account?
Is payable on death vs transfer on death better for avoiding probate?
Does a bank account beneficiary override a will in Florida?
Can I have a TOD bank account in Florida?
Are POD and TOD accounts considered non probate assets?
Can a POD beneficiary access the account before the owner dies?
Can I name my revocable trust as the POD or TOD beneficiary?
What happens if I name a minor as a POD beneficiary in Florida?
Work With a Florida Estate Planning Attorney
POD and TOD designations are a powerful first step, but they work best as part of a coordinated plan. When beneficiary forms, a will, and a trust all point in the same direction, your family avoids probate, avoids conflict, and knows exactly what to do. If you have recently lost a loved one and are sorting out which accounts pass by designation and which must go through court, the guide on probate vs. trust administration can help you understand what comes next.
Attorney Yanitza Schoonover helps Florida families review every account title and beneficiary designation, coordinate them with a properly funded revocable living trust, protect the family home with a Lady Bird deed, and plan ahead for the risk of Medicaid estate recovery. A short review today can prevent an outdated designation from sending money to the wrong person tomorrow.
Call (305) 299-7496 or email info@estateplanningattorney.us to schedule a free initial consultation. Phone and Zoom appointments are available Monday through Sunday, 8:00 AM to 9:00 PM.
The Schoonover Law Firm, P.A. | 6303 Waterford District Drive, Suite 400, Miami, FL 33126 | Florida Bar #124081